
Money questions often begin with an everyday problem: a bill arrives before payday, savings never seem to grow, or an investment sounds promising but feels difficult to understand.
If you searched for finance www disquantified .org, you may be looking for the website’s finance articles and wondering whether they can help. Disquantified.org publishes a finance archive, with separate navigation links for Finance Advisor and Investing. Its visible coverage includes financial learning, evaluating online advice, and checking whether information is outdated.
This guide explains how to approach that content and turn financial reading into useful decisions. The budgeting, saving, and investing principles below draw on consumer education resources from the Consumer Financial Protection Bureau (CFPB) and the U.S. Securities and Exchange Commission (SEC).
What Is Disquantified.org?
Disquantified.org is a publishing website with a dedicated finance section. The pages reviewed contain articles and category listings; those pages alone do not establish that the publisher provides regulated financial services. Disquantified
For readers, the useful distinction is between learning about money and receiving advice based on their own finances. An article can explain a concept, but it cannot assess your full income, obligations, family needs, or tolerance for losses.
Approach the site with a specific question. “How can I plan for irregular bills?” gives your reading a clearer purpose than simply looking for ways to become wealthy.
Finding Finance Articles
Start with the Finance archive. The archive reviewed includes articles about finding finance posts, evaluating sources, and spotting outdated financial information.
You can also use a search engine with a focused query such as site:disquantified.org budgeting. Check the destination address before opening a result, particularly when similar website names appear.
Once you find an article, follow its evidence. A link to a bank’s current fee schedule is more useful for checking a fee than another blog repeating the same number.
Start With Your Budget
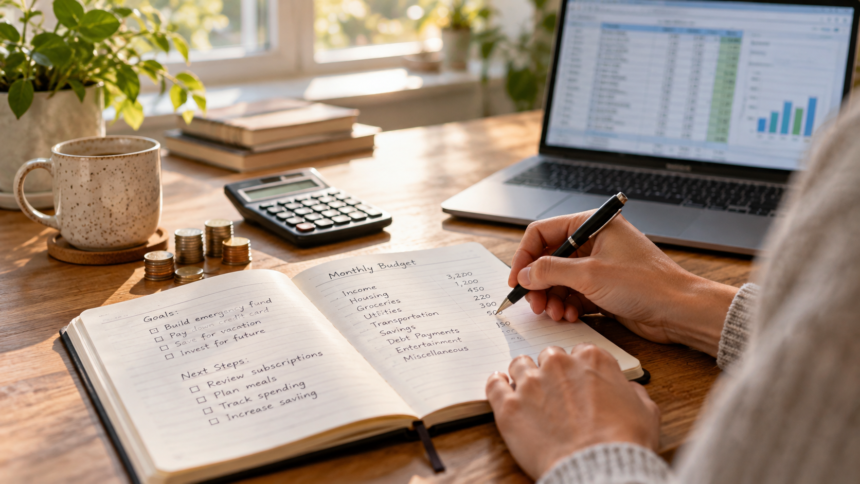
A useful budget shows both how much money you have and when you need it. The CFPB’s cash flow worksheet focuses on tracking income and expenses week by week, carrying each ending balance into the following week. consumerfinance.gov
Begin with a month of actual records. Include everyday spending, required payments, and money set aside for future costs. Estimates are a starting point, but statements and receipts give you something firmer to work with.
Consider a hypothetical household earning $2,000 a month. If it spends $1,800 and sets aside $100 for an annual bill, only $100 remains available. Ignoring that future bill would make its spending room look twice as large.
Timing matters, too. A monthly total may look comfortable even when several payments fall due before the next paycheck. A weekly view helps reveal that gap.
Build your budget around your circumstances. If basic costs already absorb your income, an unrealistic savings target will not make the numbers work.
Build Emergency Savings
An emergency fund is money reserved for unplanned expenses or an interruption in income. The CFPB explains that the right amount depends on your situation and that even a small reserve can provide some protection.
Choose an initial goal connected to a real concern, such as a repair you have struggled to pay for before. A reachable first target can make saving feel more manageable.
Keep the money somewhere safe and accessible. If you automate contributions, match them to your income schedule and monitor your balance so transfers do not trigger overdraft fees. These are practical considerations highlighted in the CFPB’s emergency savings guidance.
The first goal is a usable cushion. You can review and increase it as your circumstances change.
Understand Your Debt
Before choosing a repayment method, write down each balance, interest rate, required payment, and due date. This makes the cost and structure of your borrowing easier to compare.
The CFPB describes two common approaches. The highest-interest-rate method, often called the debt avalanche, focuses extra payments on the most expensive debt first. The snowball method starts with the smallest balance to create visible progress.
The tradeoff matters. Targeting expensive debt can save money over time, while clearing smaller balances may help some people stay motivated. The snowball approach can cost more because the highest-rate debt may remain outstanding longer.
For either approach, keep required payments on other accounts in view. A repayment plan needs to work alongside rent, utilities, food, and other obligations.
Learn Investing Basics
Investment articles are easier to assess when you begin with your goal. What is the money for, when might you need it, and how much loss could you tolerate?
Investor.gov explains that appropriate investment products depend partly on your goals, timeframe, and risk tolerance. It also identifies risk, fees, diversification, and liquidity as factors to consider. Liquidity means how easily you can sell an investment and access the money.
Diversification spreads money among different investments to help manage risk. It does not make investing risk-free: investment losses remain possible.
Fees deserve close attention. The SEC explains that investment charges reduce the money left earning returns, so seemingly small ongoing costs can have a substantial effect over time. Read product disclosures and compare the cost of buying, holding, and selling.
Understanding an investment should come before buying it. If an explanation leaves you unable to describe the risks or costs, keep asking questions.
Check the Evidence
When reading finance www disquantified .org content, assess each article on its own merits. A polished page or confident tone does not verify its claims.
Look for a named author, relevant experience, clear sources, and a publication or update date. Follow links to the underlying material rather than relying only on the article’s summary.
Match the source to the claim. Product charges should be checked against provider disclosures. Tax statements should be checked against the relevant tax authority. Investment rules should be checked with the regulator responsible for your market.
The CFPB and SEC sources used here are U.S. resources. Their educational explanations can be useful more broadly, but local account protections, taxes, and regulations require local verification.
Make Reading Useful
Choose one task after finishing an article. You might map next month’s bill dates, compare two account fee schedules, or list your outstanding debts.
For example, imagine discovering that an annual expense of $240 repeatedly disrupts your budget. Setting aside $20 each month would cover that amount over a year, assuming the cost stays unchanged. That is a simple illustration of turning information into a plan.
Review what happened after a month. Did the plan fit your income? Did an expense get missed? What needs adjusting?
You do not need to improve every part of your finances at once. A clear, repeatable action gives your reading a practical purpose.
FAQs
What does “finance www disquantified .org” mean?
It is a search phrase referring to finance content on Disquantified.org. The site has a dedicated Finance archive and navigation links for related topics.
Can beginners use Disquantified.org?
Beginners can explore its finance articles, but should check definitions, evidence, and examples before applying what they read. Start with a question relevant to your current needs.
Is Disquantified.org a financial adviser?
The publishing pages reviewed do not establish that it offers regulated financial advice. Verify any claimed adviser credentials through the relevant regulator before relying on a professional service.
Does it offer financial tools?
This review confirmed article listings and navigation. It did not independently verify working calculators, portfolio services, or downloadable budgeting tools.
How much should I save for emergencies?
There is no single amount that fits everyone. The CFPB recommends considering your circumstances and the unexpected expenses you have faced before; even a small amount can help.
Which debt repayment method is better?
The highest-interest-rate method targets costly debt, while the snowball method prioritizes smaller balances for momentum. Consider both the potential cost and your ability to maintain the plan.
Can finance articles guarantee investment success?
No. Investments involve risk, and you can lose money. Use articles to improve your understanding, then examine the actual product, fees, risks, and suitability for your goals.
Read also UGGControMan Controller From Under Growth Games: What Can Be Verified?